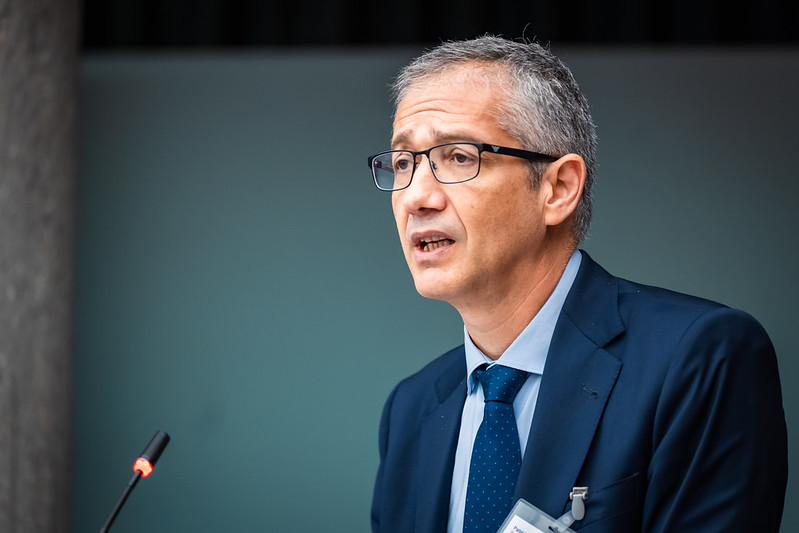
By David Barwick – VIENNA (Econostream) – High public debt, the growing role of non-bank financial institutions and digital innovation could make it increasingly difficult for central banks to distinguish market dysfunction requiring intervention from justified repricing of risk, Bank for International Settlements General Manager Pablo Hernández de Cos said Monday.
Speaking at the SUERF Annual Lecture in Vienna, de Cos said elevated government debt could complicate crisis management because sharp rises in sovereign yields might reflect either concerns over fiscal sustainability or temporary market dysfunction, such as forced deleveraging.
“If market dysfunction threatens financial stability or monetary transmission, central banks need to intervene,” he said. But when debt and government financing needs are high, “even a well-designed operation can be interpreted through a fiscal lens,” he said.
De Cos said public debt was near postwar highs in many economies, while large deficits and spending pressures from ageing and investment were likely to persist, increasing sovereign bond markets’ sensitivity to changes in investors’ assessment of fiscal risk.
He said the growing importance of non-bank financial institutions was reinforcing the problem. NBFIs were now the largest holders of sovereign debt in advanced economies, while leveraged investors such as hedge funds had become important intermediaries in several major government bond markets, he said.
According to de Cos, the interaction between sovereign bond markets, fiscal repricing and financial stability had created a new “fiscal-financial stability nexus,” through which stress could spread rapidly through funding markets and across borders, as well as between banks and non-banks.
Government bond liquidity could disappear suddenly when adverse fiscal news interacted with leveraged positions, margin calls and constrained dealer balance sheets, he said. In such circumstances, fiscal space could shrink well before limits implied by longer-term fundamentals were reached.
The expansion of NBFIs also posed a direct challenge for traditional central bank liquidity frameworks, de Cos said, because access to emergency liquidity was generally limited to deposit-taking institutions.
Where stress originated among non-banks, central banks might therefore have to rely on asset purchases rather than lending facilities, even though purchases could be difficult to calibrate and unwind, he said.
At the same time, extending central bank liquidity access to NBFIs would be problematic unless their regulation and supervision were strengthened, de Cos said.
“[E]xpecting central banks to step in without closing the regulatory gap […] is highly problematic,” he said, warning that doing so could create moral hazard, encourage regulatory arbitrage and produce an uneven playing field.
De Cos called for “congruent regulation,” under which institutions posing similar financial stability risks would face comparably stringent requirements regardless of their legal form or business model. He said further progress was still needed on reforms aimed at preventing NBFIs from undermining financial stability.
“Fiscal discipline is a key prerequisite,” de Cos said, arguing that governments should put public finances on credible and sustainable paths and build buffers during favorable periods. That would both reduce the likelihood that heavy debt issuance disrupted markets and lower the risk that any subsequent central bank intervention was perceived as serving fiscal objectives, he said.
De Cos also said technological change could make financial crises unfold considerably faster. Digital banking and social media allowed depositors and investors to transfer funds almost instantly while information, including false or incomplete information, could spread rapidly, he said.
The unprecedented speed of deposit withdrawals during the banking turmoil of 2023 illustrated the potential interaction between online banking and rapid information dissemination, de Cos said.
Stablecoins could create another potential source of stress, he said. If issuers were forced to sell reserve assets rapidly, pressure could spread to money markets and potentially require central banks to intervene to prevent a broader tightening of financial conditions. De Cos said the risk remained modest for now but could grow if stablecoins became more widely used for payments or as stores of value.
He also warned that widespread reliance on similar artificial-intelligence models for trading, risk management, liquidity planning and portfolio allocation could increase herd behavior and amplify market moves during shocks.
On central bank crisis tools, de Cos said authorities were considering new emergency lending facilities or broader access to existing ones, but interventions should observe a “backstop principle”: central banks should prevent market dysfunction from damaging the real economy without undermining price discovery or normal market risk management.
He said separating asset purchases aimed at restoring market functioning from purchases intended to provide monetary stimulus was particularly important when financial stress coincided with above-target inflation.
The Bank of England’s temporary purchases during the 2022 liability-driven investment crisis provided a useful blueprint, he said, pointing to strict limits on the duration and size of purchases as well as clear communication and governance.
De Cos said central banks should more clearly distinguish market-functioning programs from monetary-stimulus programs and could design quantitative easing in a more state-contingent manner, including clearer exit conditions and greater reversibility of purchase targets.